Pakistani Rupee Strengthens to Rs 276.57 Against US Dollar as Global Currency Markets Remain Volatile
- The Pakistani rupee appreciated by 0.01% against the US dollar on Monday, November 16, 2026, closing at Rs276.57 in the interbank market, up three paisa from the previous session.
- The local currency also recorded a weekly gain of 0.02%, while the US dollar index climbed to 103.44, its highest level since April 2025.
- International oil prices declined, with Brent crude falling to $95.30 per barrel and US WTI crude slipping to $88.34 amid expectations of improving global supplies.
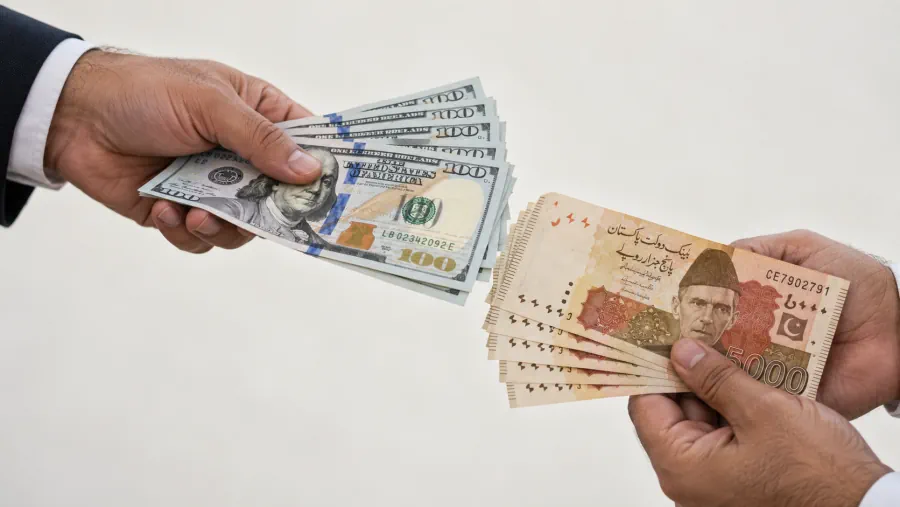
The Pakistani rupee maintained its gradual recovery against the US dollar on Monday, November 16, 2026, registering a marginal appreciation in the interbank foreign exchange market despite continued strength in the American currency internationally.
According to the latest exchange rate figures, the rupee closed at Rs276.57 against the US dollar, gaining three paisa compared with Friday’s closing rate of Rs276.60.
Also Read:
The improvement represented a 0.01% appreciation during the trading session, extending the local currency’s recent pattern of modest gains against the greenback.
The latest movement followed another week of relative stability in Pakistan’s foreign exchange market, during which the rupee strengthened slightly against the dollar.
According to data released by the State Bank of Pakistan (SBP), the local currency appreciated by 0.02% during the previous week, closing at Rs276.60 compared with Rs276.66 a week earlier.
The six-paisa weekly improvement indicated that the rupee continued to trade within a narrow range, with relatively limited fluctuations in the interbank market.
The latest closing rates show that the Pakistani currency has gained nine paisa against the dollar over the period covered by the two reported weekly and daily movements.
| Trading period | USD to PKR closing rate | Rupee movement |
|---|---|---|
| November 16, 2026 | Rs276.57 | +Rs0.03 |
| November 13, 2026 | Rs276.60 | +Rs0.06 over the week |
| November 6, 2026 | Rs276.66 | Previous weekly benchmark |
The rupee’s latest performance came as international currency markets remained focused on developments in the United States, Japan and other major economies.
The US dollar continued to demonstrate strength against several major currencies following hawkish statements from Federal Reserve officials and stronger-than-expected American inflation figures for October.
The inflation data reinforced market expectations that the US central bank could introduce further monetary tightening to control rising consumer prices.
The US Dollar Index, which measures the greenback’s performance against a basket of six major currencies, climbed to 103.44, reaching its highest level since April 2025.
The index’s advance reflected renewed demand for the American currency as investors assessed the possibility of higher US interest rates.
Market expectations have increasingly shifted towards another interest rate increase at the Federal Reserve’s upcoming monetary policy meeting.
According to CME Group’s FedWatch tool, federal funds futures indicated a 93.9% probability of a 25-basis-point interest rate increase at the Federal Reserve meeting scheduled to conclude on December 9.
The probability of a larger 50-basis-point increase stood at approximately 6%, declining from 11.5% recorded on Friday.
These expectations followed comments from Federal Reserve policymakers suggesting that additional action could be necessary to contain inflationary pressures in the American economy.
Meanwhile, the Japanese yen remained under pressure against the US dollar, trading close to its lowest level in two months following weaker-than-expected economic growth figures from Japan.
The Japanese currency fluctuated within a limited range during early Asian trading on Monday, with investors assessing the implications of an unexpected contraction in Japan’s economy during the third quarter.
The yen traded at approximately 159.69 against the US dollar and 176.04 against the euro, remaining near levels at which American and Japanese authorities were believed to have intervened in currency markets earlier this year.
Japan’s economy contracted at an annualised rate of 0.1% during the July-to-September quarter, compared with market expectations of 0.3% growth.
The disappointing economic figures raised questions about Japan’s monetary policy outlook and the potential direction of interest rates.
Most other major currencies showed limited movement during early Asian trading.
The euro traded at approximately $1.1025 against the US dollar, while the British pound remained steady at $1.3216.
The Australian dollar was largely unchanged at $0.6777, while the New Zealand dollar traded near $0.5523.
| Currency | Exchange rate against USD |
|---|---|
| Euro (EUR) | $1.1025 |
| British Pound (GBP) | $1.3216 |
| Australian Dollar (AUD) | $0.6777 |
| New Zealand Dollar (NZD) | $0.5523 |
| Japanese Yen (JPY) | ¥159.69 per USD |
International oil prices also moved lower on Monday, reflecting expectations of improving global crude supplies and signs of weaker demand from China.
Brent crude futures declined by 54 cents, or 0.6%, to $95.30 per barrel by 0427 GMT.
US West Texas Intermediate (WTI) crude futures also fell, losing 22 cents, or 0.3%, to trade at $88.34 per barrel.
The decline followed expectations of a potential supply surplus as oil shipments from the Middle East through the Strait of Hormuz moved closer to their pre-war levels.
The restoration of shipping activity through the strategically important waterway has contributed to expectations of improved crude availability in international markets.
At the same time, data showing a decline in Chinese refinery throughput during October suggested softer demand for crude oil from one of the world’s largest energy consumers.
Lower international oil prices can influence Pakistan’s external payments because petroleum products account for a significant portion of the country’s import requirements.
Changes in global energy prices can affect the country’s import bill, foreign exchange demand and broader economic conditions, although their eventual impact depends on domestic pricing policies, exchange rates and international market developments.