PM Youth Loan Scheme: Here’s how to get Rs75 lakh for businesses and farmers across Pakistan
Young entrepreneurs and farmers across Pakistan can apply for financing of up to Rs75 lakh under the Prime Minister’s Youth Business and Agriculture Loan Scheme. The programme covers new ventures and existing businesses seeking funds to expand. National Bank of Pakistan (NBP), one of the participating lenders, is promoting the two higher financing tiers in its advertisement.
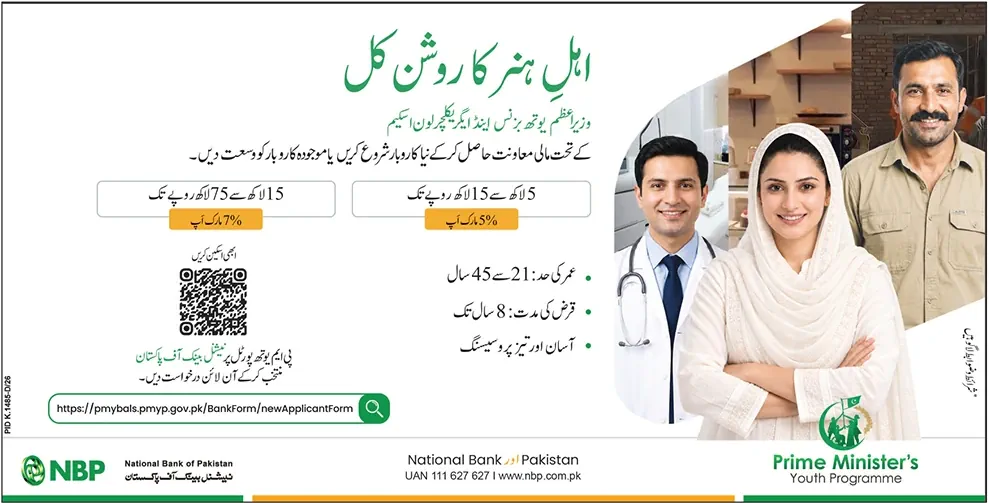
- Business and agriculture loans are available at 0%, 5% and 7% markup, depending on the amount borrowed.
- Pakistani residents aged 21 to 45 can apply, with a lower age limit of 18 for IT and e-commerce businesses.
- Applications are submitted online, and eligible long-term loans can be repaid over up to eight years.
The business and agriculture scheme has three tiers. Tier 1 offers up to Rs5 lakh at zero markup. Tier 2 covers loans above Rs5 lakh and up to Rs15 lakh at 5% markup, while Tier 3 covers loans above Rs15 lakh and up to Rs75 lakh at 7% markup. Participating microfinance banks and institutions process and disburse Tier 1 loans. The scheme earmarks 25% of loans for women borrowers.
Also Read:
| Loan tier | Loan amount | Markup | Maximum repayment period | Applicant contribution for a new business |
|---|---|---|---|---|
| Tier 1 | Up to Rs5 lakh | 0% | 3 years. Crop loans have a 1-year limit. | 10% |
| Tier 2 | Above Rs5 lakh to Rs15 lakh | 5% | 8 years for long-term or development loans. Up to 5 years for working capital, production and murabaha financing. | 20% |
| Tier 3 | Above Rs15 lakh to Rs75 lakh | 7% | 8 years for long-term or development loans. Up to 5 years for working capital, production and murabaha financing. | 20% |
Applicants must be Pakistani citizens residing in the country, hold a valid CNIC and generally be between 21 and 45 years old. For IT and e-commerce businesses, the minimum age is 18 and applicants need at least matriculation or an equivalent qualification. The age requirement applies directly to individuals and sole proprietors. For partnerships and companies, at least one owner, partner or director must meet it. Government employees are ineligible.
Businesses can use the loans for long-term investment, working capital, Islamic financing arrangements such as murabaha, and locally manufactured vehicles for commercial use. Civil works can account for up to 65% of the total financing limit. The scheme generally allows one financed vehicle per borrower, with an exception for food franchise and distribution businesses. Agricultural loans cover production and development in sectors including crop farming, livestock, poultry, fisheries and dairy.
Eligible business borrowers can take one long-term loan and one short-term loan within the overall Rs75 lakh cap. Farmers can similarly obtain one production loan and one development loan within the same combined limit.
Tier 1 loans generally run for up to three years, with repayment in equal monthly instalments. Tier 1 crop loans can run for up to one year and are repaid in a lump sum on or before maturity, in line with the crop cycle. Long-term and development loans in Tiers 2 and 3 can run for up to eight years, including a grace period of up to one year. Working capital, production and murabaha financing in those tiers can run for up to five years. Banks may structure working capital and production loans so borrowers pay only markup for the first two years, followed by principal and markup over the next three.
For a new business, applicants must contribute 10% of the project cost under Tier 1 or 20% under Tiers 2 and 3. The contribution can be made in cash or immovable property after loan approval. The scheme has no minimum equity requirement for existing businesses. Tiers 1 and 2 generally require a personal guarantee, while Tier 3 security requirements depend on the lender’s credit policy. Any vehicle financed under the scheme serves as collateral.
Applicants must complete the bilingual application form on the Prime Minister’s Youth Programme portal. They should enter their CNIC details, select the financing tier and participating lender, and provide the requested personal, business and financial information. Applicants who want NBP to assess their request can select the bank where it appears as an option. Applications are accepted online only.
Applicants should prepare a passport-size photograph and clear copies of both sides of their CNIC. The form also asks for educational and experience certificates, licences and trade registrations where applicable. Existing businesses must provide a recommendation letter from the relevant chamber, trade body or union.
Applicants should have their National Tax Number and the consumer ID from the electricity bill for their home and, where applicable, their business premises. They should also have the registration numbers of any vehicles registered in their name. The form asks for the names, CNIC numbers and mobile numbers of two references who are not blood relatives.
New businesses should provide estimates of monthly business income, operating costs, household expenses and any other income. Existing businesses should provide actual figures. Applicants should review all entries before submitting the form, as errors can affect processing. The scheme rules set a non-refundable processing fee of Rs100, including NADRA verification, and a processing period of up to 45 days. Applicants can check their status on the portal using the CNIC number, mobile number, CNIC issue date and date of birth provided on the form.
The scheme also has a separate Tier 4 for laptops and prospective overseas workers. The laptop facility offers up to Rs150,000, Rs300,000 or Rs450,000, depending on the category and actual cost, at zero markup over up to four years. It covers students aged 18 to 30 at institutions recognised by the Higher Education Commission. Banks can also assess business plans from freelancers and young entrepreneurs seeking laptop financing.
Prospective overseas workers aged 21 to 45 with a verified job offer can apply for up to Rs10 lakh at zero markup over up to five years. The loan can cover training, travel, visa and settlement expenses. Both Tier 4 facilities require a 20% applicant contribution and a personal guarantee from a family member. Prospective overseas workers can apply through a dedicated form on the programme portal.